INVEST COMPOUND · ACADEMY
What Is a Recession? A Practical Guide for Investors
What is a recession? Learn how economic downturns are identified, why they happen, how they can affect stocks, jobs and credit, and how investors can prepare without relying on recession predictions.
What is a recession? A recession is a significant decline in economic activity that spreads broadly through the economy. It can affect employment, household income, consumer spending, corporate profits, lending conditions and business investment.
If you are asking what is a recession, the most useful answer is that it is a broad economic contraction affecting more than GDP alone. Employment, income, spending, production and business activity can all weaken.
A recession is not the same thing as a falling stock market. Markets can decline before a recession begins, recover while economic conditions remain weak, or move very differently from the economy altogether.
For investors, this distinction matters. Knowing that a recession may occur does not tell you exactly when stocks will fall, when they will recover, or which asset class will perform best.
A more useful approach is to understand the economic cycle and build household and portfolio resilience before conditions become stressful.
What Is a Recession?
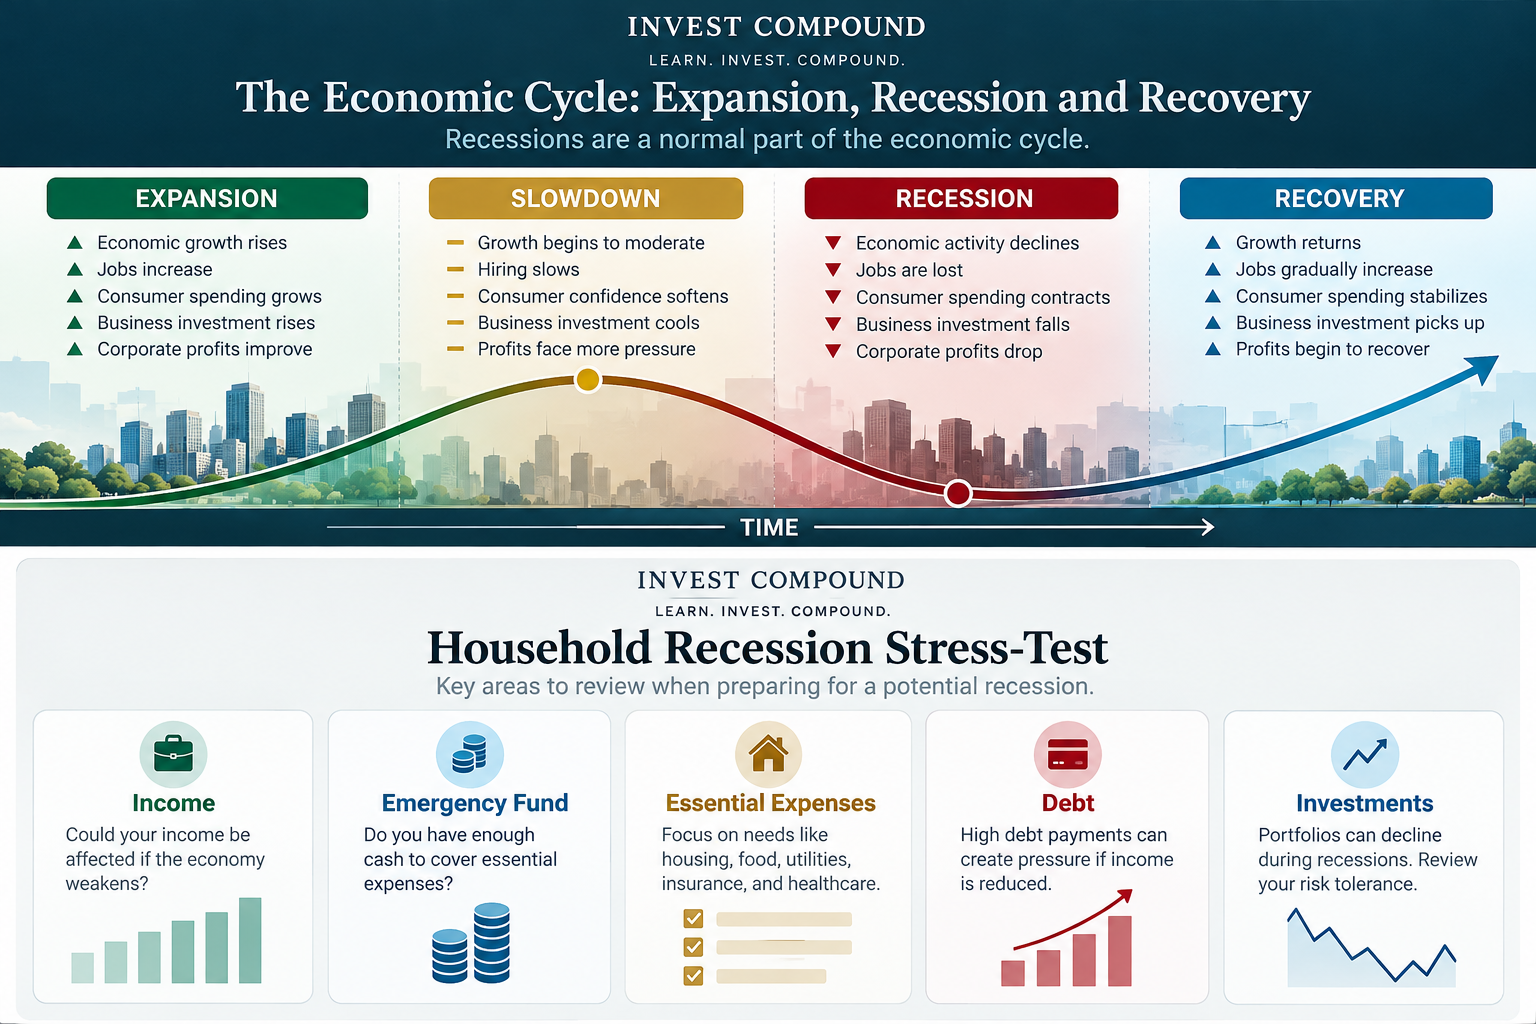
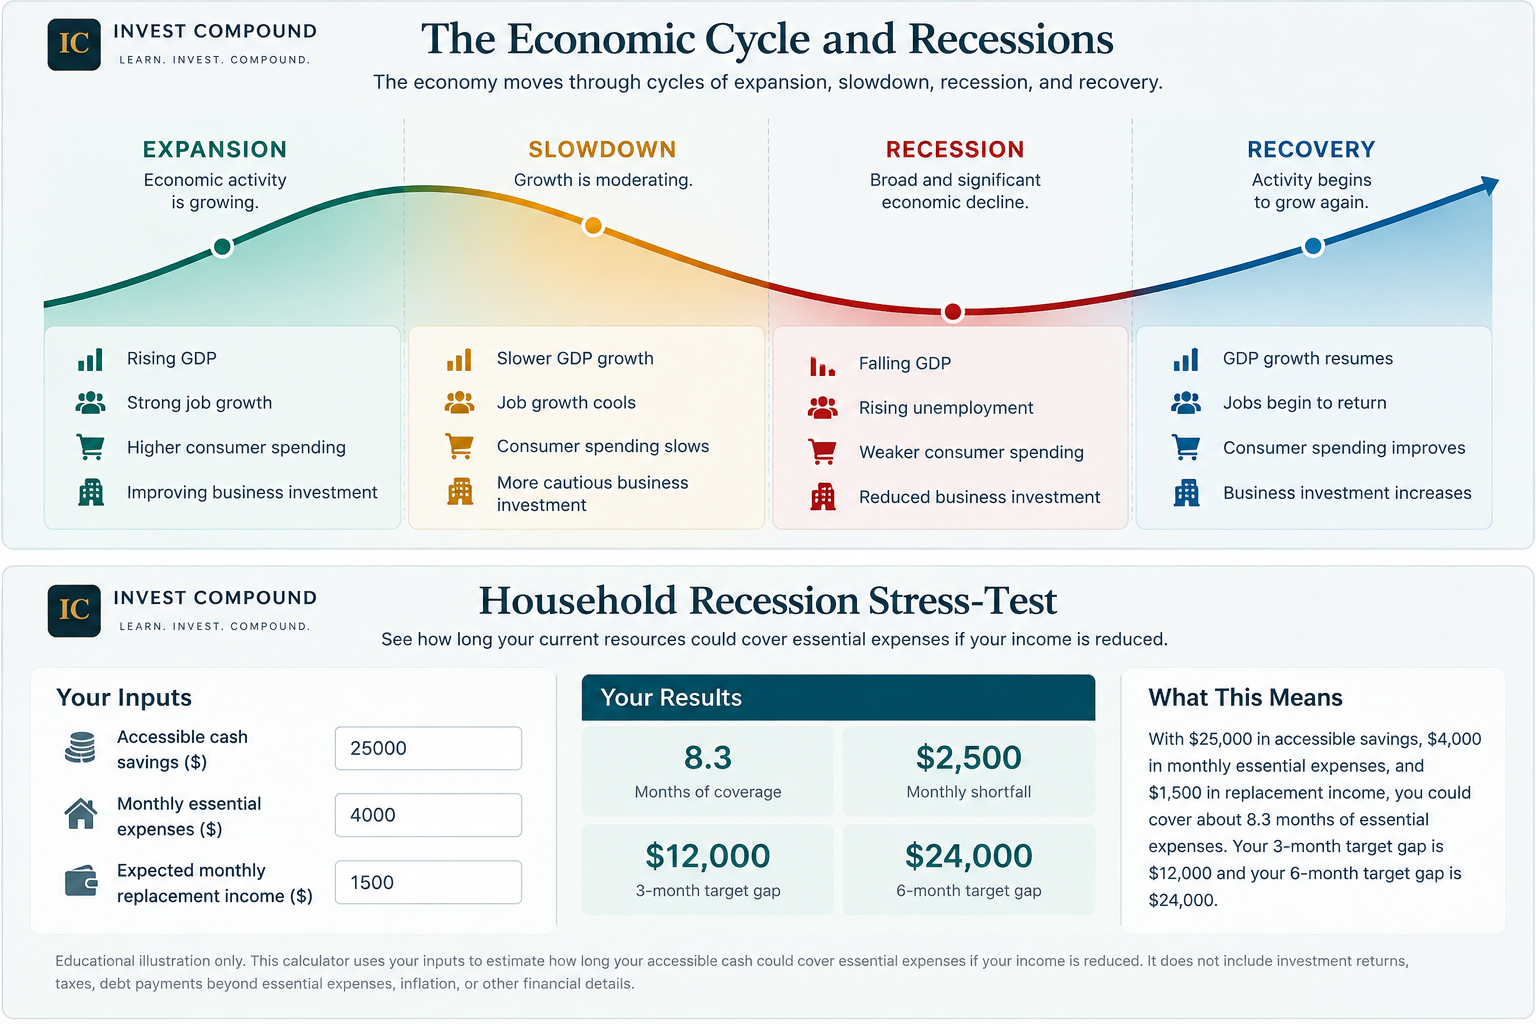
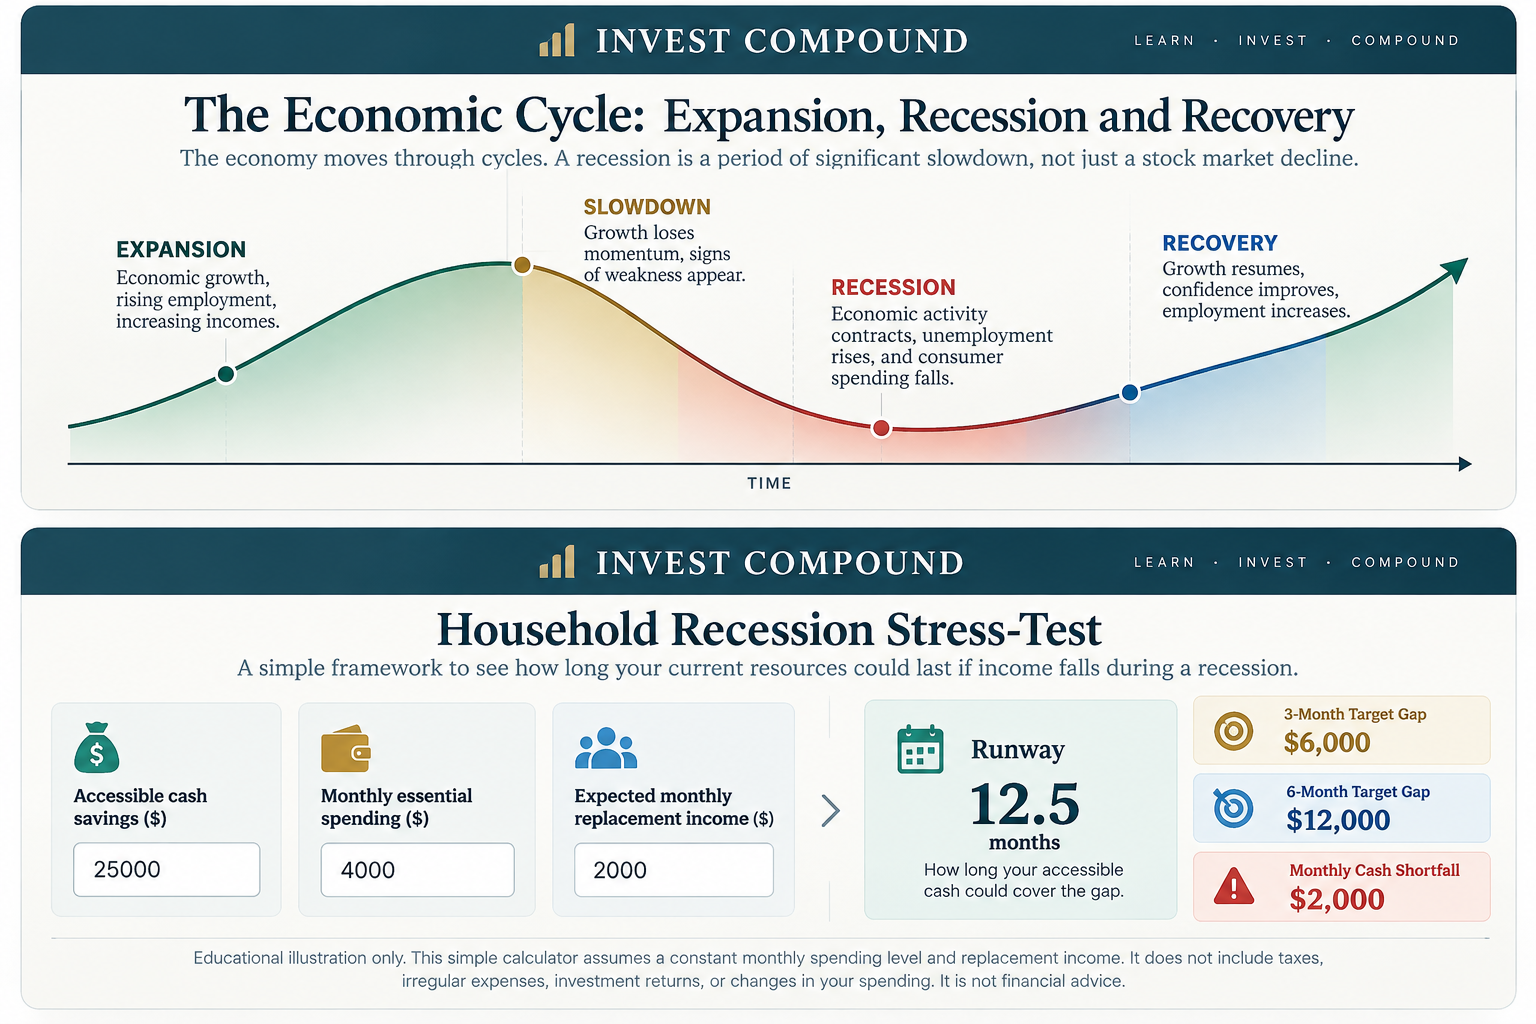
Understanding what is a recession also means understanding where recessions fit within the broader economic cycle. Expansion can give way to slower growth, economic contraction and eventually recovery.
In the United States, the National Bureau of Economic Research, or NBER, maintains the widely followed chronology of business-cycle peaks and troughs.
Its traditional recession definition focuses on a significant decline in economic activity that is spread across the economy. The assessment considers the depth, diffusion and duration of the downturn.
The popular rule that a recession means two consecutive quarters of negative real GDP is therefore a shortcut, not the formal NBER test.
Canada also does not rely on a simple two-quarter formula. The C.D. Howe Institute’s Business Cycle Council evaluates whether declines in economic activity are persistent, pronounced and pervasive, considering duration, amplitude and scope.
What Happens During a Recession?
No two recessions are identical, but several economic pressures often appear during a downturn.
Inflation often falls when demand weakens, but not always. A downturn can coexist with elevated inflation when the economy is also dealing with supply constraints, energy shocks or other cost pressures. That environment is sometimes described as stagflation.
Why Do Recessions Happen?
There is rarely one universal cause.
Different recessions can begin with very different economic problems.
| Possible Driver | How It Can Affect the Economy |
|---|---|
| Credit or Asset Bust | Excess borrowing or inflated asset prices can reverse, damaging balance sheets and reducing spending. |
| Monetary Tightening | Higher interest rates can restrain borrowing, housing, consumer demand and business investment. |
| External Shock | Events such as pandemics, commodity shocks, wars or supply disruptions can reduce economic activity. |
| Financial Stress | Banking or credit problems can reduce the availability of financing and weaken confidence. |
| Falling Confidence | Households and businesses may cut spending at the same time, reinforcing an economic slowdown. |
How Long Do Recessions Last?
Recessions vary enormously in severity and duration.
The U.S. recession associated with the initial COVID-19 shock was exceptionally brief. The NBER dated the peak of economic activity to February 2020 and the trough to April 2020.
The 2007–2009 recession lasted much longer and was connected to severe financial-system and housing-market stress.
Historical averages can provide context, but they are a poor basis for assuming how long a future recession will last.
More importantly for households, the duration of an official recession may be very different from the duration of an individual’s job search, income loss, business slowdown or portfolio drawdown.
What Happens to Stocks During a Recession?
The relationship between a recession and the stock market is not synchronized.
Stock prices are forward-looking. Investors continuously estimate future earnings, interest rates, inflation and economic conditions. Markets can therefore begin falling before economic activity reaches an official peak.
The reverse is also possible: stocks may begin recovering while unemployment remains high and economic reports are still weak.
Some sectors may behave differently during recessions. Consumer staples, healthcare and utilities are often described as more defensive because demand for many of their products and services may be less economically sensitive.
Travel, autos, industrial businesses and discretionary spending can be more cyclical.
But sector labels are not guarantees. Company balance sheets, debt levels, valuations, margins and management decisions still matter.
Dividend-paying companies can also reduce dividends if profits and cash flow weaken sufficiently.
For broader market context, see How the S&P 500 Works .
Signs of a Recession Investors Watch
Knowing what is a recession does not mean investors can identify one perfectly in advance. Economic indicators often provide useful signals, but none offers a guaranteed forecast.
There is no single indicator that reliably predicts every recession.
Analysts commonly follow a combination of:
- employment and unemployment claims,
- real income,
- industrial production,
- consumer spending,
- business surveys,
- credit conditions and defaults,
- corporate earnings,
- housing activity, and
- the yield curve.
What Does an Inverted Yield Curve Mean?
A yield-curve inversion occurs when some shorter-term government bond yields rise above longer-term yields.
Inversions have historically received significant attention because they have preceded a number of U.S. recessions.
But the timing can vary substantially, and an inversion does not tell an investor precisely when a recession or stock-market decline will begin.
Economic forecasts should therefore be treated as estimates rather than certainties.
How to Prepare for a Recession Financially
For most households, preparation is more useful than prediction.
A household does not need to correctly forecast the next recession to improve its financial resilience.
Build Accessible Cash Reserves
An emergency fund can help cover essential expenses when employment income is interrupted.
Three to six months of essential expenses is often used as a general planning reference, but the appropriate amount depends on individual circumstances.
Someone with irregular income, dependants, concentrated employment risk or limited access to alternative financing may prefer a larger reserve.
Know Your Essential Spending
Separate necessary spending from discretionary spending.
Essential costs may include:
- housing,
- food,
- utilities,
- insurance,
- debt payments,
- necessary transportation, and
- healthcare.
Knowing this number gives an emergency fund a practical meaning.
Reduce Expensive Debt
High-interest debt creates a fixed obligation regardless of what the economy or stock market is doing.
Reducing expensive revolving debt can increase flexibility before an economic downturn arrives.
Review Employment Risk
Income risk is sometimes overlooked because investors focus heavily on market risk.
Keep professional skills, certifications, contacts and employment records current. Review benefits, severance arrangements and insurance before they are needed.
How Can Investors Prepare Their Portfolio for a Recession?
For investors studying what is a recession, the practical question is not only whether economic activity may decline, but whether their portfolio and household finances can withstand that decline.
Investing during a recession does not require predicting the exact market bottom.
A stronger starting point is to ensure that the portfolio already reflects the investor’s time horizon, liquidity needs and ability to tolerate losses.
Match Risk to Your Time Horizon
Money that may be needed soon should generally not depend entirely on stock-market performance.
If a household needs to sell equities during a major decline to pay necessary expenses, the portfolio may have been carrying more liquidity risk than the household could comfortably support.
Diversify
Diversification cannot eliminate market losses, but it can reduce dependence on the outcome of one company, industry or narrow investment theme.
Diversification can extend across companies, sectors and asset classes, depending on the investor’s objectives.
Rebalance According to a Plan
Market declines change portfolio weights.
Rebalancing according to a predetermined allocation can restore the intended risk profile without requiring a forecast of the market bottom.
See Asset Allocation Explained With Portfolio Examples for more detail.
Continue Contributions Only When Affordable
Regular investing during market declines can purchase more shares at lower prices, but household solvency comes first.
If income falls, reducing or temporarily pausing contributions may be appropriate.
That is very different from selling an entire portfolio simply because a recession is predicted.
Stress-Test Income and Investments Together
One of the biggest weaknesses in recession planning is evaluating the investment portfolio separately from employment and household finances.
In reality, the risks can occur together.
Suppose a household has essential expenses of $3,000 per month and $15,000 in accessible cash.
Without other income, that reserve represents approximately five months of essential spending.
Now assume employment income disappears while a $50,000 equity portfolio falls by 30%.
The investment account would temporarily be worth about $35,000.
Having accessible reserves can reduce the pressure to sell those investments during the decline.
Correlated Risks Matter
Imagine both members of a household work in the same industry.
If the sector weakens during a recession, both incomes may be exposed simultaneously.
If their investments are also heavily concentrated in the same sector, employment income and investment values can deteriorate together.
Property can add another layer of correlation. Rental income can decline, vacancies can increase, repairs still need to be paid, and a property may not be easy to sell quickly.
Recession planning should therefore consider the whole household balance sheet.
Think About Liquidity, Not Just Net Worth
A household can have substantial net worth but still experience a cash problem.
Property, retirement accounts, private investments and other assets may be difficult, expensive or undesirable to liquidate quickly.
Accessible liquidity serves a different purpose from long-term investments.
Why Can Stocks Rise While Economic News Is Still Weak?
One of the most confusing features of recessions is that the stock market and the economy can appear to move in opposite directions.
Stock prices reflect expectations about the future.
Suppose investors expect a severe economic contraction. If new economic data remain weak but are less bad than expected, asset prices can rise.
Markets may also anticipate:
- lower interest rates,
- slower inflation,
- improving corporate earnings,
- better credit conditions, or
- an eventual economic recovery.
The reverse can also occur. Economic data may appear healthy while stock prices fall because investors expected even stronger results or because valuations and interest rates changed.
Economic Data Can Be Revised
GDP, employment, income and business surveys arrive on different schedules.
Early estimates can also be revised.
This is another reason a recession label should not automatically become a buy or sell instruction.
Review Businesses for Financial Resilience
When examining an individual company during a potential recession, focus on its ability to endure weaker conditions.
Useful questions include:
- How much cash and liquidity does the company have?
- When does its debt mature?
- How sensitive is revenue to the economic cycle?
- Can operating cash flow cover interest and essential expenses?
- Does the company need to refinance soon?
- How concentrated are its customers?
- Does it have meaningful pricing power?
Two companies can report similar earnings yet have very different financial resilience because their debt structure and liquidity differ.
Accounting profit and liquidity are not the same thing.
What Not to Do During a Recession
Do Not Panic-Sell Everything
Selling an entire portfolio because economic headlines are frightening converts temporary market prices into permanent investment decisions.
It also creates a second difficult decision: deciding when to buy back.
Do Not Borrow Simply to “Buy the Dip”
Lower prices do not guarantee that prices cannot fall further.
Leverage creates fixed repayment obligations precisely when employment, income or asset prices may already be under pressure.
Do Not Assume the Next Recession Will Look Like the Last One
The cause, inflation environment, interest-rate backdrop, financial system and policy response can all differ.
Do Not Ignore Income Risk
A 20% portfolio decline may attract attention, but job loss can have a much larger immediate effect on household cash flow.
Do Not Wait for an Official “All Clear”
Economic turning points are often confirmed after they occur.
Waiting for certainty can mean making investment decisions after prices have already adjusted.
Frequently Asked Questions About Recessions
What is a recession?
A recession is a significant and broadly distributed decline in economic activity. In the United States, the NBER examines multiple indicators and considers depth, diffusion and duration.
Is a recession always two negative quarters of GDP?
No. Two consecutive quarters of falling real GDP are commonly used as a shorthand, but that is not the formal NBER definition used for U.S. business-cycle dating.
Is a recession the same as a bear market?
No. A bear market generally refers to a decline of at least 20% from a recent market high. A recession refers to economic activity. They can overlap, but one does not mechanically require the other.
Do stocks always fall during a recession?
No. Stocks often experience significant volatility around recessions, but the timing is inconsistent. Markets can fall before a recession is identified and may recover while economic data are still weak.
Should investors stop investing during a recession?
Not automatically. Whether contributions remain appropriate depends on the investor’s income, emergency reserves, debt, time horizon and overall financial plan.
How much emergency savings should I have before a recession?
Three to six months of essential expenses is a commonly cited planning range, but there is no universal amount. Job stability, dependants, debt, insurance and access to other income sources can materially change an appropriate reserve.
Are bonds always safe during recessions?
No. Bond performance depends on interest rates, duration, credit quality, inflation and issuer risk.
Learn more in How Bonds Work .
Can anyone reliably predict the next recession?
Economic indicators can help assess risk, but recession timing remains uncertain and forecasts frequently disagree. Building a plan that can survive several plausible outcomes is generally more robust than depending on one forecast.
Key Takeaways
- A recession is a broad economic contraction, not simply a declining stock market.
- Understanding what is a recession requires looking at economic activity across employment, income, spending, production and business conditions rather than relying on one indicator.
- Two negative GDP quarters are a useful shorthand but not the formal U.S. recession-dating rule.
- Recessions vary greatly in cause, depth and duration.
- Stocks may decline before a recession and recover before economic conditions visibly improve.
- No single indicator reliably predicts the beginning or end of every recession.
- Emergency savings and household cash flow can reduce the need to sell long-term investments during a downturn.
- Employment risk, debt, investments and liquidity should be stress-tested together.
- Diversification and appropriate asset allocation reduce dependence on correctly forecasting the economic cycle.
- Preparing for a recession is generally more practical than trying to predict one perfectly.
LEARNING LAB · HYPOTHETICAL
Emergency-Fund Runway Calculator
Estimate how long accessible savings could cover the gap between essential monthly expenses and expected replacement income.
Educational illustration only. The calculator assumes constant essential spending and replacement income. It does not include taxes, investment returns, inflation, irregular expenses, debt changes, insurance benefits or other financial details.
Continue Learning in the Invest & Compound Academy
Explore research on recessions, inflation, monetary policy, and long-term investing.
Economic cycles and market education
Inflation and real returns | Rates and stock valuations | Portfolio allocation | Bond fundamentals | Market indexes | Stock-market basics
Sources and Further Reading
- National Bureau of Economic Research – Business Cycle Dating FAQ
- National Bureau of Economic Research – Business Cycle Dating
- C.D. Howe Institute – Business Cycle Council Methodology
- U.S. Bureau of Economic Analysis – Gross Domestic Product
- U.S. Bureau of Labor Statistics – Employment and Unemployment